Independent appraisal · Statewide
New York Insurance Appraiser: a second, independent number for your property claim
When the carrier accepts your claim but its estimate won’t pay for the repair, New York Insurance Appraiser re-scopes the loss from the ground up and takes the difference through the appraisal clause in your policy.
- Your appointed appraiser
- Homes, co-ops, condos & commercial
- All 62 counties
Covered isn’t the same as paid
Why owners call a New York Insurance Appraiser instead of arguing alone
Most short claims aren’t denials. They’re estimates with a slope missing, a ceiling priced as patch-and-paint, a co-op wall assigned to the wrong policy, or an ice-dam leak written up as “maintenance.” New York Insurance Appraiser works the space between “we’ll cover it” and a check that actually rebuilds.
We start from our own inspection, never an edited copy of the carrier’s file, and we price what we can defend in front of an umpire. If your problem is a denial or a deadline, we’ll say so on the first call and point you to the right professional.
How our practice worksStart with your situation
Who New York Insurance Appraiser works for
The appraisal clause reads the same for everyone, but a Park Slope brownstone, a Midtown co-op and a Rochester strip mall raise very different questions.
 HomeownersHouses, two-families and attached homes with a short or stalled claim.See how we help
 Co-op & condo boardsMaster-policy losses, unit-to-unit leaks and board-managed buildings.See how we help
 Business ownersStorefronts, offices, mixed-use and multifamily property claims.See how we help
 Attorneys & adjustersIndependent valuation, estimate review and umpire appointments.See how we help
Appraisal & estimating
Eleven services from one New York Insurance Appraiser
Every stop on this line leads to the same destination: a valuation of your loss that holds up. Some clients need the whole route; many only need an estimate review.
- 1Appraisal Clause RepresentationWe act as your named appraiser after either side invokes the appraisal clause in a New York property policy.
- 2Homeowners Claim AppraisalIndependent valuation of dwelling, garage, fence and contents losses for New York houses, rowhouses and two-families.
- 3Co-op, Condo & Commercial AppraisalAppraisal for co-op boards, condo associations, managing agents, mixed-use, retail and multifamily owners in New York.
- 4Roof & Hail Damage AppraisalIndependent hail damage appraisal for roofs, siding, gutters and skylights across the Hudson Valley, Capital Region and Western NY.
- 5Windstorm & Tornado AppraisalWind damage appraisal after derechos, microbursts, tornadoes and severe thunderstorms anywhere in New York State.
- 6Hurricane & Nor’easter AppraisalHurricane claim appraisal for coastal New York, with careful attention to wind versus surge and percentage deductibles.
- 7Water Damage AppraisalWater damage claim appraisal for burst and frozen pipes, appliance leaks, unit-to-unit leaks and sewer backup losses in NY.
- 8Fire & Smoke Damage AppraisalFire damage appraisal for New York homes and attached buildings, including smoke migration, contents and living expenses.
- 9Snow Load & Ice Dam AppraisalIce dam claim appraisal for lake-effect snow, roof collapse and freeze-up losses, a distinctly New York kind of claim.
- 10Insurance Estimate ReviewAn independent insurance estimate review that shows where the carrier’s number falls short before you decide on appraisal.
- 11Umpire ServicesNeutral insurance appraisal umpire services for New York panels where the two appraisers cannot agree on the amount of loss.
Regional knowledge
From the boroughs to the Great Lakes: six claim climates
A New York Insurance Appraiser has to know how a Sandy-era South Shore roof, a Syracuse snow load and a Bronx riser leak each show up in an estimate.
New York City
- Unit-to-unit water
- Fire & smoke migration
- Flash flooding
- Wind-driven rain
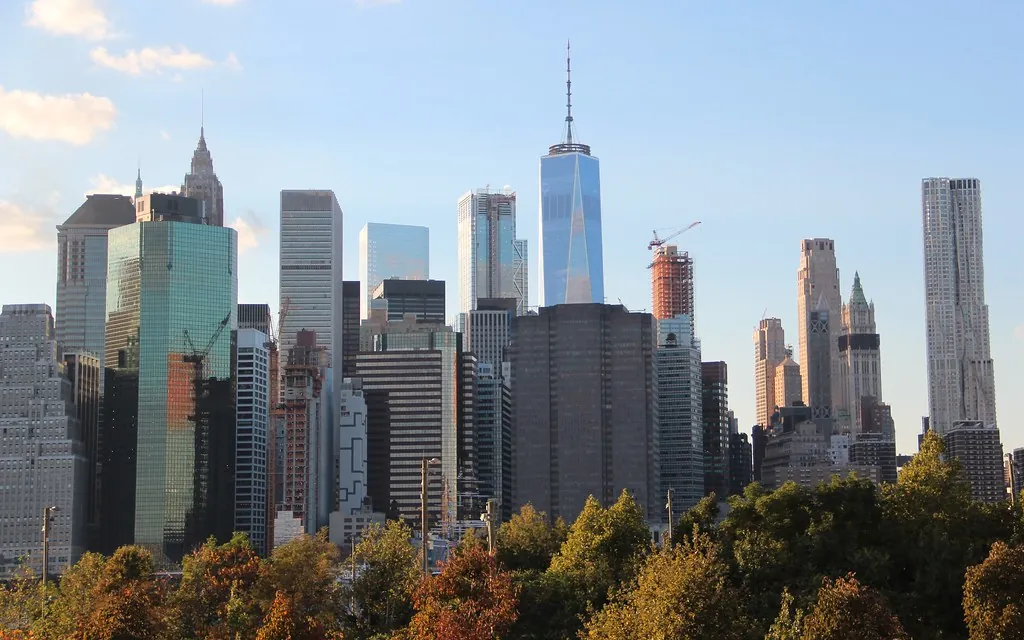
Co-ops, condos, brownstones and attached brick homes put two or three policies on every loss. A burst riser in a pre-war co-op or a fire next door in a Brooklyn row means sorting the board’s master policy from your own before anyone can price the damage.
Long Island
- Hurricane deductibles
- Nor’easters
- Tree fall
- Wind vs. surge
South Shore communities still measure storms against Sandy. Percentage hurricane deductibles, wind-versus-flood questions and big oaks over capes and high-ranches drive most of the disputes we see east of the city line.
Hudson Valley & Westchester
- Severe thunderstorms
- Falling trees
- Hail
- Basement water
Leafy suburbs mean limbs on roofs. Summer squall lines, the occasional tornado and cloudburst flooding like the remnants of Ida leave older colonials and Tudors with layered roofs, finished basements and complicated scopes.
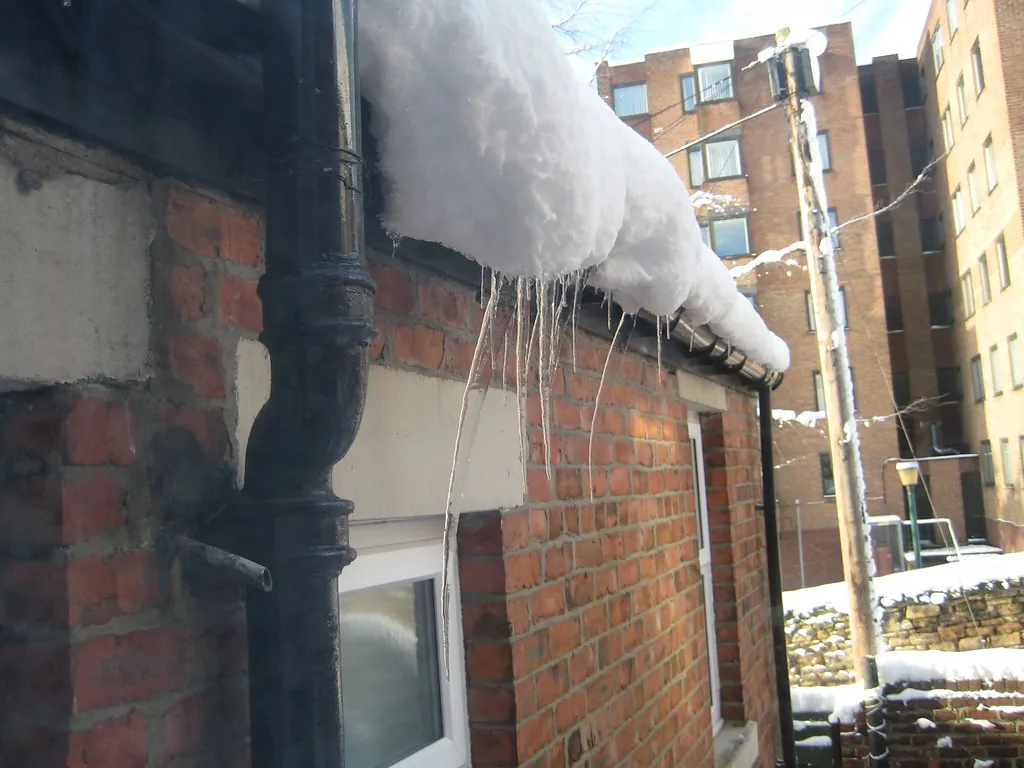
Capital Region & North Country
- Ice dams
- Ice storms
- Frozen pipes
- Hail
Freeze–thaw cycles do quiet, expensive damage to Albany brick rowhouses and Adirondack camps alike. Ice dams, burst pipes in vacant seasonal homes and ice-loaded trees are the claims winter leaves behind.
Central NY & Finger Lakes
- Lake-effect snow load
- Derecho winds
- Ice dams
- Hail
Some of the snowiest large cities in the country sit along the Thruway. Heavy, wet lake-effect loads stress older wood-frame roofs, and summer derechos like the 1998 Labor Day storm show how fast wind claims pile up.
Western NY & Southern Tier
- Blizzards
- Roof collapse
- River-valley water
- Wind
Buffalo doubles under multi-foot lake-effect snow and Southern Tier homes along the Susquehanna share one thing: losses where cause matters. Separating covered snow, ice and wind damage from excluded flooding is often the whole dispute.
Storm record
Storms that still shape New York claims
Each of these events left a lesson about how damage gets scoped, priced and argued. A New York Insurance Appraiser reads every new claim with them in mind.
- 1938Long Island ExpressLong Island
The hurricane that reshaped the South Shore and still anchors how coastal wind risk is priced.
- 1998Labor Day derechoCentral NY
Straight-line winds across Syracuse showed that inland wind claims can rival a coastal storm.
- 2011Irene & LeeCatskills · Southern Tier
Back-to-back storms flooded the Schoharie Valley and Binghamton, and tested the line between flood and covered water.
- 2012Superstorm SandyNYC · Long Island
Surge, wind and the Breezy Point fire in one event made cause-of-loss the central claim question.
- 2014“Snowvember”Buffalo area
Several feet of lake-effect snow in days brought roof collapses, ice dams and interior water claims.
- 2021Remnants of IdaQueens · Westchester
Record cloudburst rainfall flooded basements, raising sewer-backup and surface-water coverage questions.
- 2022Buffalo blizzardWestern NY
Hurricane-force gusts and whiteout snow left frozen pipes, wind damage and long-delayed inspections.
Before you demand appraisal
Three questions a New York Insurance Appraiser asks first
- Has the carrier accepted coverage?Appraisal values a covered loss. A denial is a coverage fight, and that usually means a New York attorney.
- Is the gap worth the cost?Each side pays its own appraiser and shares the umpire. Run the numbers in the box.
- Can you document it?Photos, measurements and a credible line-item estimate move awards. Opinions don’t.
Want fees included? Try the settlement gap & fee estimator.
The route
How New York Insurance Appraiser moves a stalled claim
Six stops from the first call to a signed award. Most panels resolve the bulk of the dispute between stops four and five.
- CallFree first conversation about the policy, the estimate and the gap.
- Re-scopeOur own inspection, measurements and photos of the loss.
- ValueLine-item estimate priced for your New York ZIP code.
- DemandAppraisal invoked in writing; we’re named as your appraiser.
- PanelLine-by-line work with the carrier’s appraiser.
- AwardTwo of three signatures set the amount of loss.
Free & private
Claim calculators from a New York Insurance Appraiser
Check the carrier’s math before you pick up the phone. Each calculator runs in your browser and nothing you type is stored or sent.
 CalculatorSettlement Gap & Fee EstimatorSee the disputed amount, a projected award and what you’d net after appraiser and umpire fees.
 CalculatorACV vs. RCV Holdback CalculatorEstimate the first actual cash value check, the depreciation held back, and the date to claim it.
 CalculatorRoof Area & Pitch EstimatorTurn a footprint and pitch into roof squares, waste, bundles and tear-off for multiple layers.
 CalculatorHurricane Deductible CalculatorConvert a 1–5% hurricane deductible into dollars and compare it with your flat deductible.
 PlannerClaim Calendar BuilderTurn your date of loss into dated claim milestones and download them as a calendar file.
 ChecklistAppraisal Readiness CheckupTwelve yes-or-no questions that score your file and build a to-do list before you demand appraisal.CalculatorCo-op & Condo Claim SplitterSplit a unit loss between the building’s master policy, your HO-6 and your own pocket.
On-site statewide
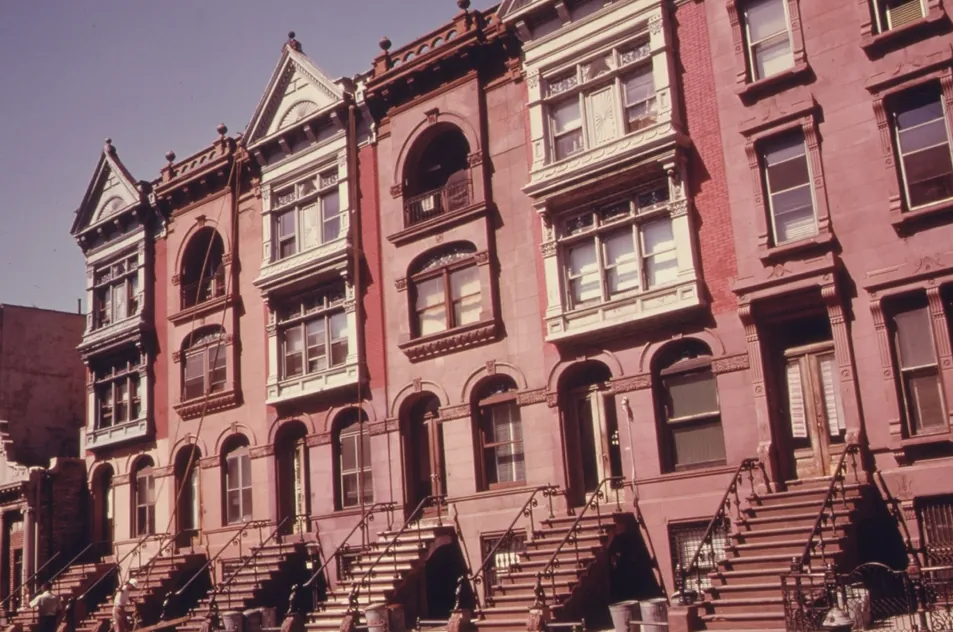
Where New York Insurance Appraiser inspects most often
We cover every county. These are the communities that call us most, each with its own housing stock and storm history.
Questions
Ask a New York Insurance Appraiser
Plain answers about the process, the cost and when appraisal is the wrong move.
What does a New York Insurance Appraiser do?
A New York Insurance Appraiser values a property loss when you and your insurer agree the damage is covered but disagree on what it costs. Once appraisal is invoked we act as your appointed appraiser: inspect, build an independent estimate, work with the carrier’s appraiser and, if needed, present open items to the umpire.
Is appraisal the same as hiring a public adjuster?
No. A public adjuster, licensed by the Department of Financial Services, manages and negotiates the whole claim. An appraiser works inside the policy’s appraisal clause on one question: the amount of loss. We don’t handle coverage disputes or give legal advice.
When is it worth calling a New York Insurance Appraiser?
When coverage is accepted, you have the carrier’s estimate, and the gap to a credible repair estimate is meaningful. Small gaps are often closed faster with a documented supplement request.
Is the appraisal award binding?
On the amount of loss, generally yes, once two of the three panel members sign. That’s why documentation matters before you invoke appraisal.
What does appraisal cost?
Each side usually pays its own appraiser and splits the umpire. Our fee is agreed in writing before any work starts, and the first conversation is free.
Does New York Insurance Appraiser cover upstate as well as the city?
Yes. We work across all 62 counties, from the five boroughs and Long Island to the Capital Region, Central New York, the Finger Lakes, Western New York and the Southern Tier.
Policyholder guides
Read this before you sign a proof of loss
Guides from New York Insurance Appraiser on New York policy language, documentation and claim strategy.
7 min readThe 1943 Standard Fire Policy and Your Appraisal RightsMost U.S. appraisal clauses were modeled on one New York statute. Here is what its standard fire policy appraisal clause says and how it plays out in a modern claim. 7 min readHow Hurricane Deductibles Work on Long Island and in NYCA percentage deductible can take a large bite out of a wind claim. Here is how a hurricane deductible on Long Island or in the city is usually triggered and calculated.
 7 min readIce Dams and Roof Leaks: Building a Stronger Winter ClaimWinter roof leaks from ice dams are common across upstate New York. Here is how an ice dam roof leak claim is usually evaluated and where disputes tend to arise.
Start with a conversation
Talk to a New York Insurance Appraiser about your claim
Tell us what happened and what the carrier offered. You’ll get a straight answer on whether appraisal is worth pursuing, with no pressure and no obligation.
- Call or text+1 (844) 537-1427
- Emailinfo@newyorkinsuranceappraiser.com
- HoursMon–Fri, 8am–6pm ET
- CoverageAll 62 New York counties